What is the market overview and industry significance of the Titanium Market?
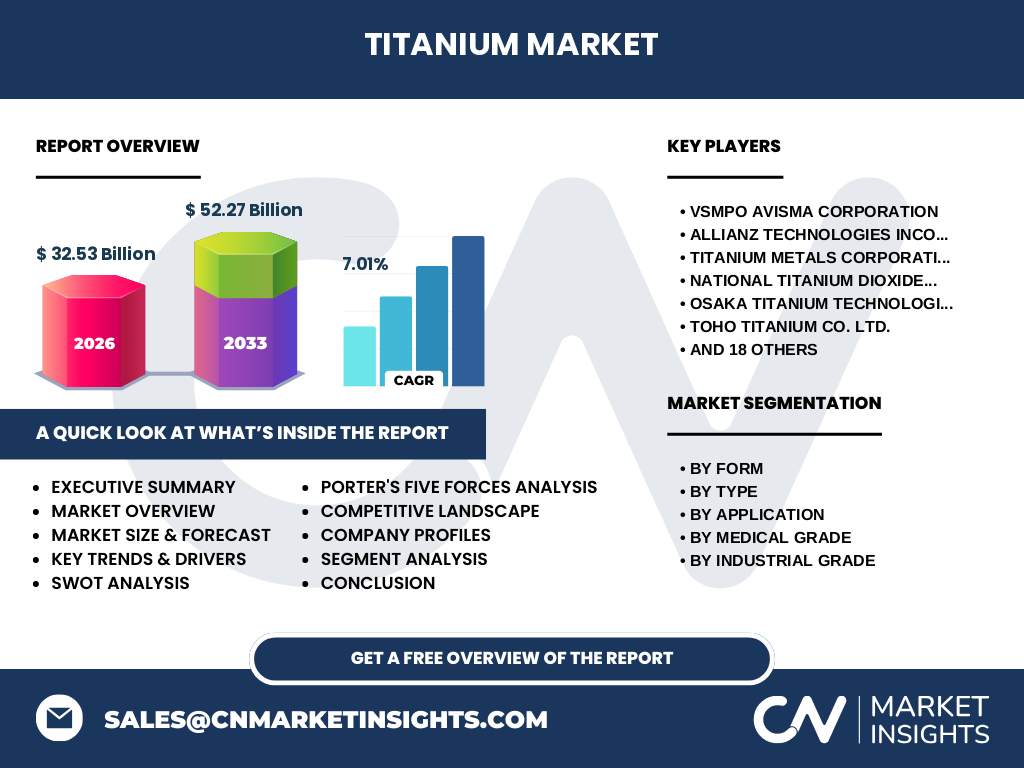
Our analysis indicates that the Titanium Market reaches a valuation of $32.53 Billion by 2026, driven by its exceptional strength-to-weight ratio and corrosion resistance. This sector is foundational for aerospace frames, marine hardware, and high-performance chemical processing infrastructure, requiring complex Kroll process reductions to convert ilmenite and rutile ores into usable metal.
Key market drivers, restraints, challenges, and opportunities shaping the Titanium Market
Growth is propelled by surging commercial aircraft deliveries and rigorous environmental mandates. However, supply chain bottlenecks for high-purity titanium sponge and volatile energy costs constrain margins. Substantial opportunities lie in expanding additive manufacturing powders and developing lightweight medical implants that offer superior biocompatibility.
Emerging trends and growth patterns in Titanium Market
The industry is witnessing an accelerated pivot toward closed-loop recycling and plasma atomization for aerospace-grade powder. Sustainability initiatives are forcing producers to adopt low-carbon reduction techniques, heavily favoring mills equipped with advanced vacuum arc remelting technologies.
COVID-19 impact analysis and recovery trajectory
The pandemic caused an unprecedented contraction in commercial aviation demand, forcing major sponge producers to slash output. Recovery has materialized through defense sector baseline funding and a rebound in chemical processing capital expenditures, stabilizing supply chains across primary global trade lanes.
Competitive landscape and strategic dynamics of major players
Market concentration remains high among vertically integrated giants. VSMPO-AVISMA and Titanium Metals Corporation (TIMET) dominate sponge and mill product output, while regional specialists like Osaka Titanium Technologies and Toho Titanium command significant shares in high-purity electronics and aerospace applications.
Executive summary of the Titanium Market
Our comprehensive research underscores a robust market trajectory, projecting growth from $32.53 Billion in 2026 to $52.27 Billion by 2033 at a 7.01% CAGR. Strategic investments in medical-grade alloys and lightweight structural components remain critical for capturing expanding margins.
Market forecast from 2027 to 2033
Based on our econometric modeling, the Titanium Market industry trends point toward sustained expansion, scaling from the 2026 baseline to $52.27 Billion by 2033. This trajectory reflects a steady 7.01% CAGR, underpinned by rising adoption in next-generation narrowbody aircraft and orthopedic implants.
Segmentation analysis across forms, types, and applications
Segmentation reveals complex downstream integration. By Form: Covers Titanium Concentrate, Titanium Tetrachloride, Titanium Sponge, Ferrotitanium, Titanium Pigment, and Other Forms. By Type: Splits into Industrial Grade and Medical Grade. By Application: Spans Paints And Coatings, Aerospace And Defense, Chemicals, Electric Power, and Other Applications. Industrial grade divides into Commercially Pure Titanium (Cp Titanium) and Titanium Alloys, while medical grade encompasses Titanium Alloys and Porous Titanium.
Regional market analysis and geographic distribution
Geographic performance is heavily anchored by aerospace manufacturing hubs and pigment consumption clusters. North America and Europe lead in high-end aerospace alloy demand, whereas Asia-Pacific dominates titanium pigment production and industrial chemical processing capacity, driven by expansive manufacturing facilities in China and Japan.
In-depth regional review of the Titanium Market
Asia-Pacific commands the volume share due to extensive pigment manufacturing by entities like Pangang Group Vanadium Titanium & Resources. Meanwhile, North American demand is propelled by defense procurement programs involving Howmet Aerospace and Carpenter Technology, requiring strict adherence to stringent military specifications.
Company profiles and strategic positioning
Industry leaders employ distinct strategies to secure supply security. VSMPO-AVISMA and TIMET leverage vast sponge capacities, while specialized firms like Norsk Titanium pioneer wire-fed additive manufacturing. Baoji Titanium Industry anchors China's domestic mill product supply chain for industrial and aerospace end-users.
Porter's Five Forces analysis of competitive intensity
Rivalry is intense among established tier-1 mill producers, yet dampened by high capital entry barriers required for Kroll process plants. Supplier power remains moderate-to-high due to limited high-grade titanium ore reserves, whereas buyer power is concentrated among major OEMs like Airbus and Boeing.
SWOT analysis of the Titanium Market
Strengths: Exceptional strength-to-weight ratio and corrosion resistance. Weaknesses: High energy intensity and complex refining costs. Opportunities: Additive manufacturing and biomedical porous implants. Threats: Substitution by advanced carbon-fiber composites and severe geopolitical trade disruptions affecting raw material supply.
Value chain analysis from raw materials to end-users
The value chain initiates with mining ilmenite and rutile, progressing through chlorine metallurgy into titanium tetrachloride and sponge. Vacuum arc remelting converts sponge into mill products like billets and sheets, which downstream fabricators shape into aerospace structural frames and chemical heat exchangers.
Investment insights and strategic recommendations
Investors should target companies specializing in scrap recycling and closed-loop manufacturing to mitigate raw material volatility. High-potential areas include porous titanium for spinal fusion devices and localized sponge production facilities designed to de-risk concentrated international supply chains.
Conclusion and key takeaways
The Titanium Market analysis demonstrates clear momentum, set to reach $52.27 Billion by 2033. Stakeholders must prioritize technological agility, sustainable processing methods, and strategic supply chain localization to successfully navigate upcoming environmental regulations and surging aerospace demand.
Research methodology for baseline estimates
Our baseline figures are triangulated using a rigorous mix of primary stakeholder interviews with procurement directors, exhaustive trade registry data from customs authorities, and secondary macroeconomic indicators tracking aerospace and chemical industry capital expenditures.
Scope of the report and coverage parameters
This report evaluates the global Titanium Market size across primary forms, grades, and end-use applications from 2026 through 2033. Geographic coverage spans North America, Europe, Asia-Pacific, Latin America, and the Middle East & Africa, excluding localized artisanal mining operations.
Recent developments and strategic moves in the industry
Recent market activity highlights increased joint ventures in aerospace supply chains and facility expansions for titanium powder production. Key players are proactively forging long-term feedstock agreements and investing in green-energy reduction processes to comply with tightening carbon emission standards.